Could my loan cost less?
Compare the whole cost
Put the current loan beside the alternatives, including ongoing fees and the cost of moving. Any estimated saving needs to account for those costs and the period you expect to keep the loan.
Home loans / Refinance
Compare your current loan with refinance options. Look at the rate, switching costs and features together, so you can decide whether moving makes sense.
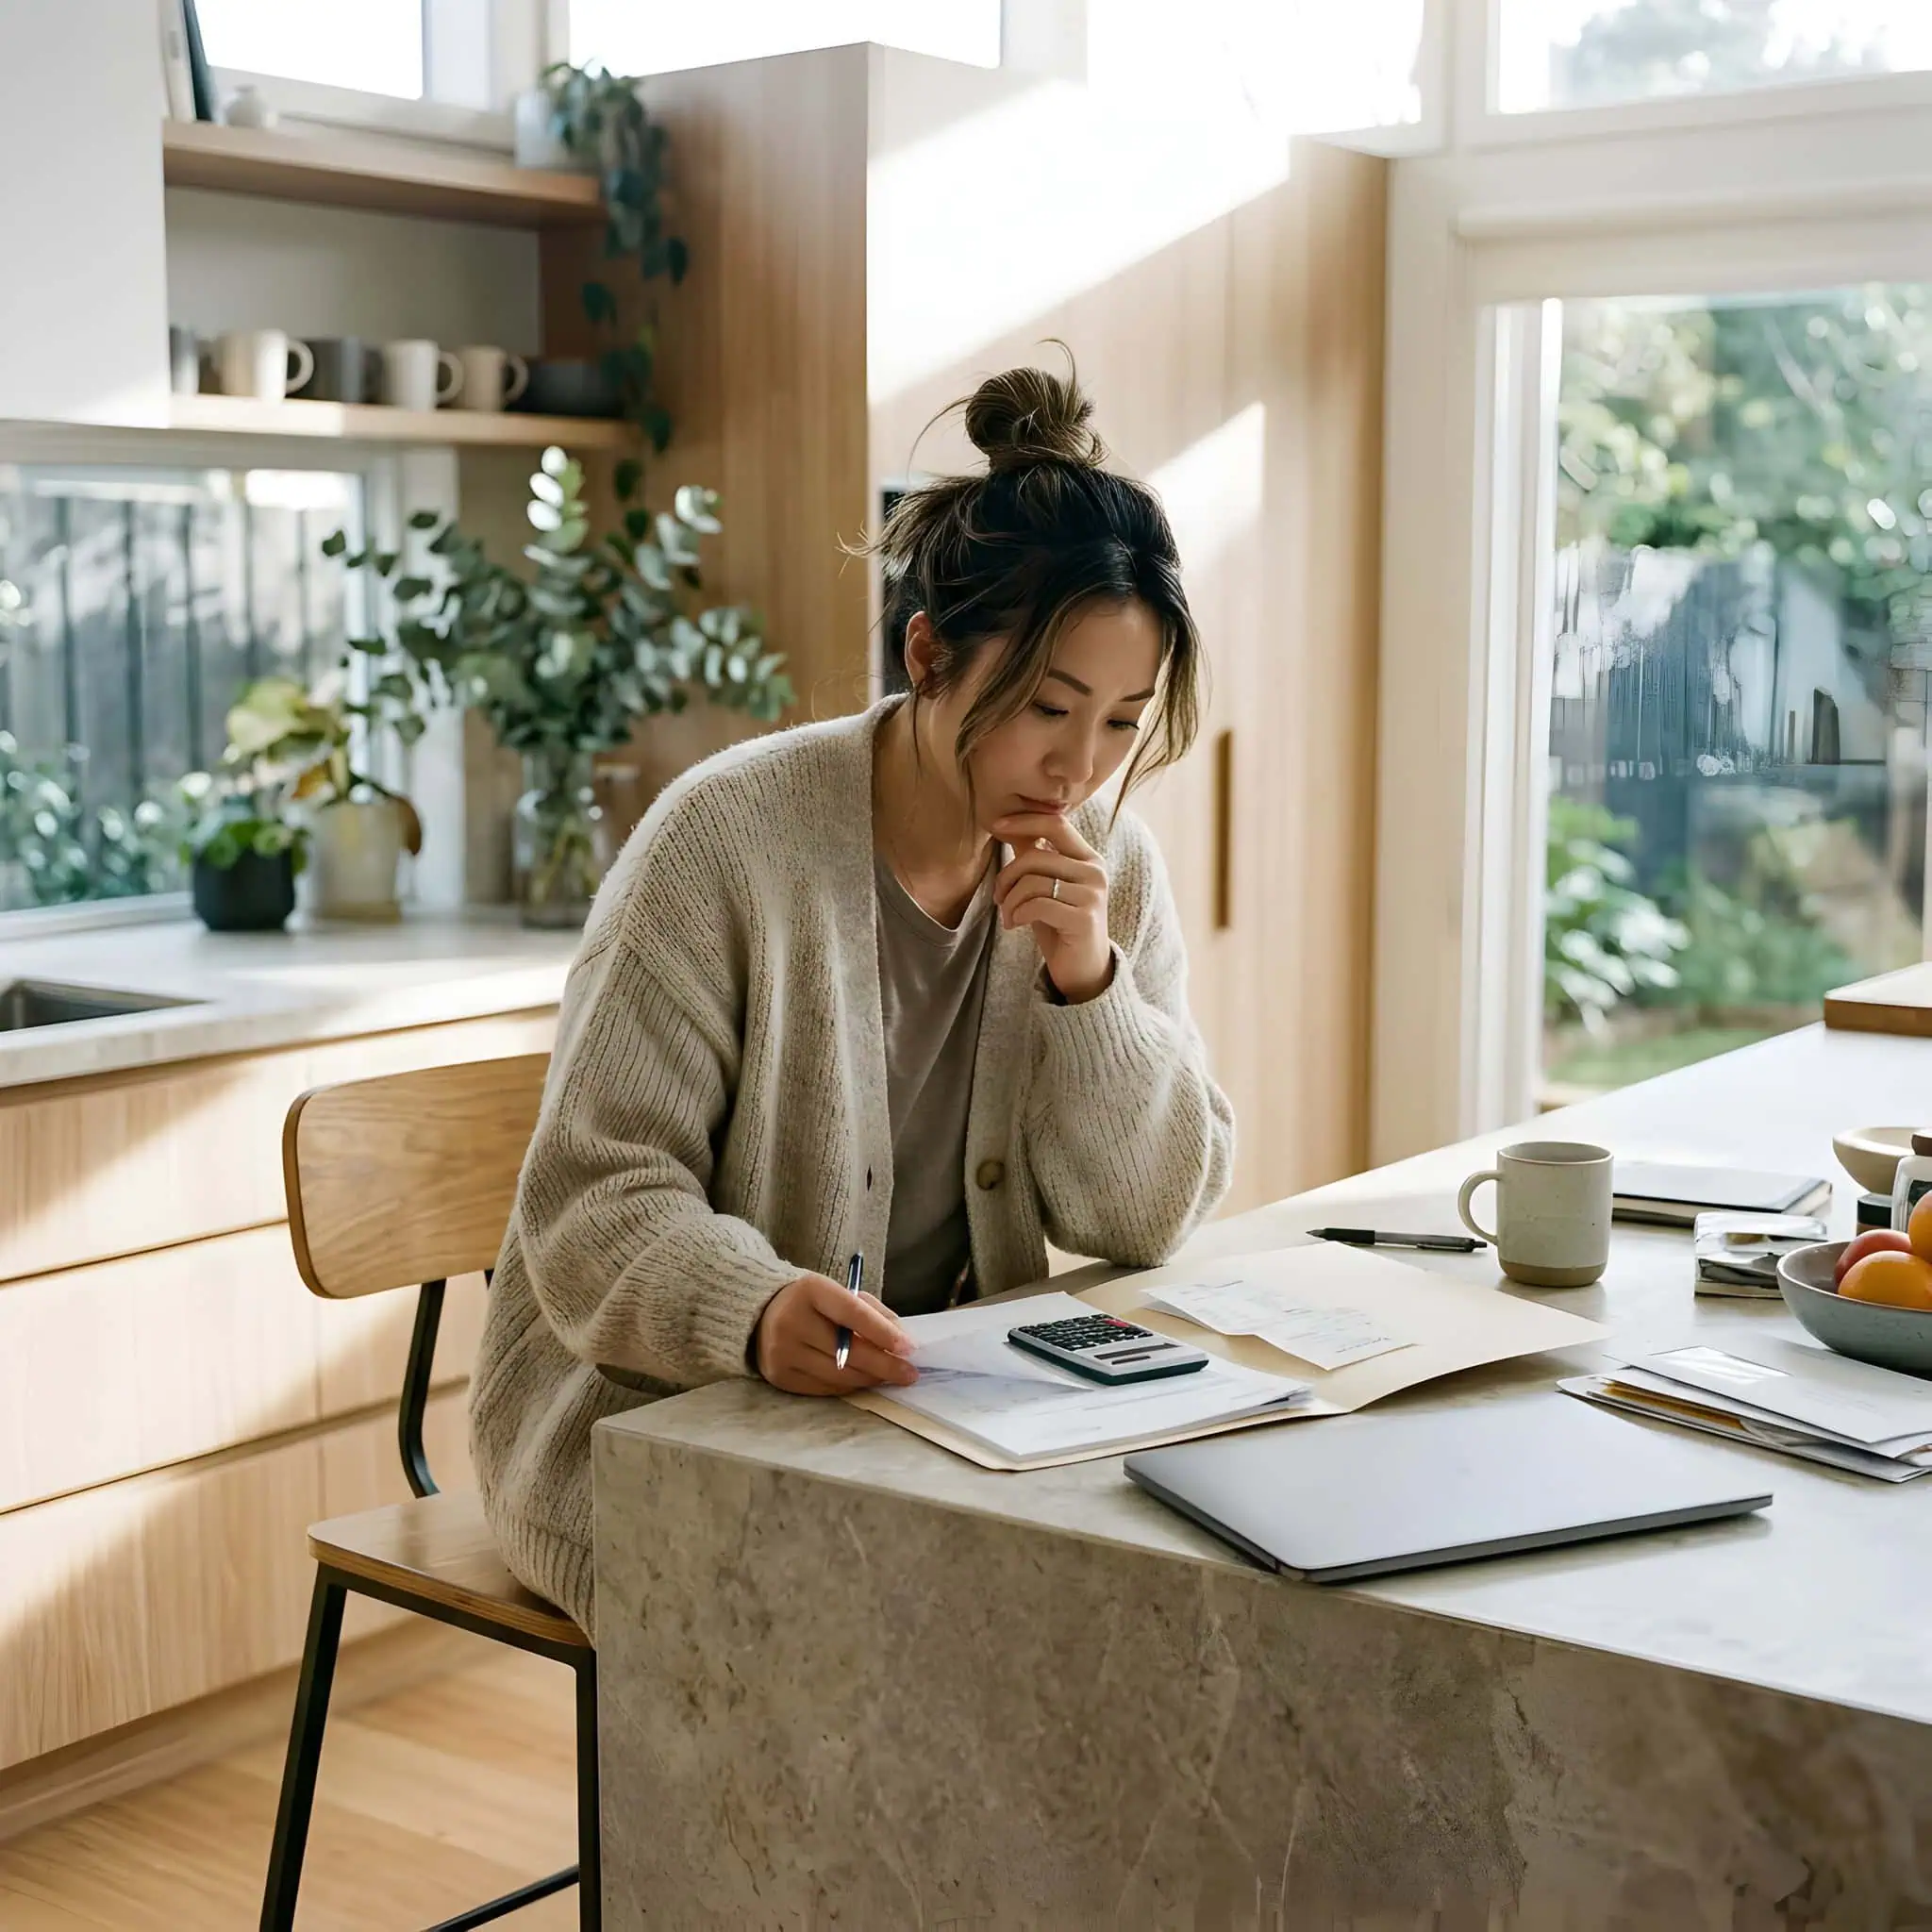
What brings you here?
A different rate is one reason to review your loan. A change in your plans can be another.
Could my loan cost less?
Put the current loan beside the alternatives, including ongoing fees and the cost of moving. Any estimated saving needs to account for those costs and the period you expect to keep the loan.
I want different features.
Consider offset, redraw, repayment flexibility and fixed or variable options alongside their fees and conditions. The right combination depends on how you manage your money.
Could I access my equity?
If you want additional borrowing, include its purpose in the review. Available equity alone does not establish eligibility; the lender still assesses the property value, your finances and the proposed loan.
Can I bring other debts together?
Debt consolidation may be considered as part of a refinance, subject to assessment. Compare the total interest, fees and repayment term, as well as the risk of securing other debts against your home.
Before you switch
Compare loans on a consistent basis and make the trade-offs visible before you decide.
Explore staying with my lenderAny comparison is based on its inputs and assumptions. A lender assesses your circumstances before deciding whether to approve a new loan.
The next steps
Start with indicative options, then work through the details with Wity before deciding how to proceed.
Tell us about your current loan, property and goals to see matched loan options. These are indicative options based on what you tell us, not a personal recommendation or approval.
Talk with the Wity team about your situation, what you want to change and the next steps. This is a discovery conversation, without a loan recommendation or credit advice.
Your adviser prepares your WityLoanPlan and explains the recommendation at a strategy meeting. Figures remain subject to verification and may change as the details are confirmed.
If you accept your loan proposal, Wity prepares the application and supporting documents for lodgement. The lender assesses the application; if approved, Wity helps coordinate the switch through settlement.
Accepting a proposal authorises preparation; it does not submit an application or guarantee approval. After settlement, your Home Loan Review provides a place to revisit your loan.
A little more clarity
A few useful answers. For the details that are specific to you, talk with our team.
Book a callKeep exploring
Start with your loan details and what you want to change. Your comparison is a starting point for deciding what to do next.
This page provides general information, not a personal recommendation. Matched loan options and estimates are indicative, based on the details supplied and subject to verification, lender eligibility and full assessment. Refinancing can involve discharge fees, break costs, new-loan fees and government charges. Savings, additional borrowing and approval are not guaranteed.