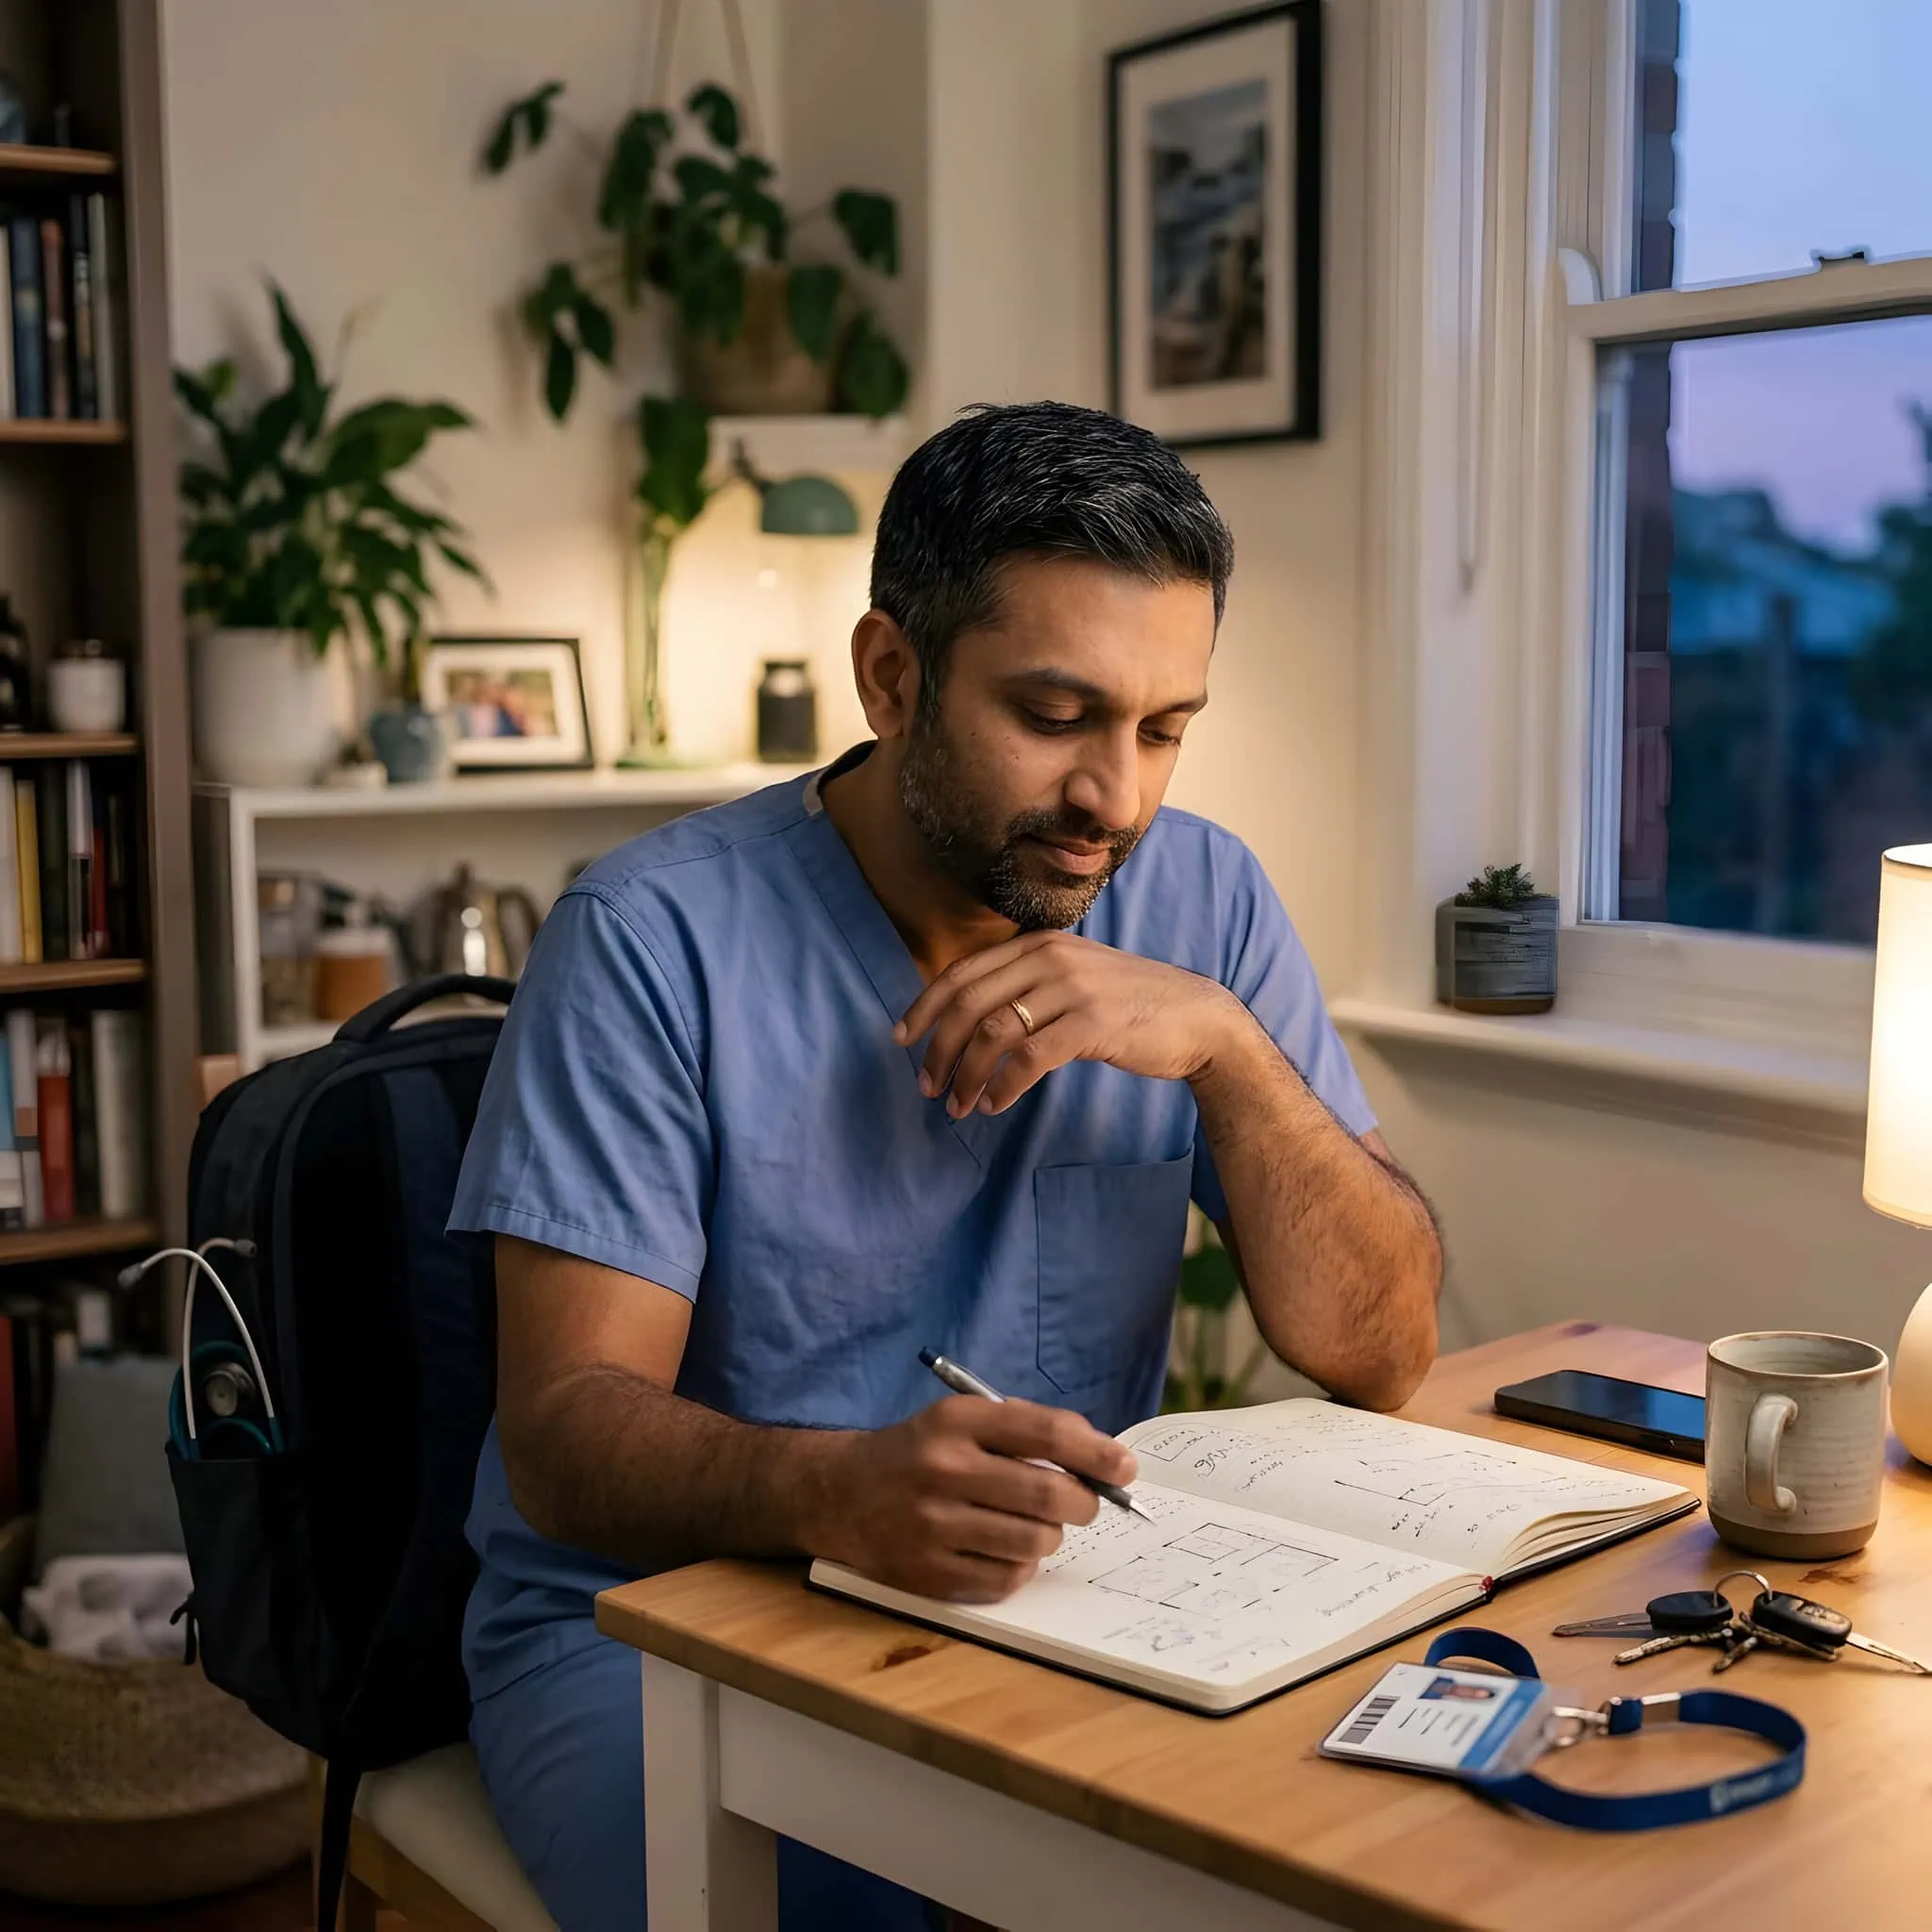
Training, locum work or running a practice? Explore home loan options with Wity and work through the income, commitments and plans that shape your next move.
Home plans alongside a demanding professional life.
/01Doctors & specialists
/02Dentists
/03Locum & practice income
Your working life
Start with how you work today.
A job title is a starting point. Your employment arrangements, household commitments and property plans help us understand the whole position.
/01
I’m a doctor still in training.
Bring your current position into focus.
Tell us about your employment contract, current earnings, study debt and deposit. If a role change is planned, bring the details so your adviser can check what evidence is relevant.
/02
I work as a locum.
Explain the pattern behind your income.
Talk through your contracts, work history and any gaps between placements. We can identify the documents needed to assess your position rather than rely on one recent payslip.
/03
I’m a dentist with practice income.
Separate the practice from the home loan.
Whether you’re an associate or a practice owner, explain how you’re paid and any business commitments. Your adviser can work through the income evidence needed for your home loan goal.
/04
My career has moved on. My loan hasn’t.
Review the loan against your next move.
A new role, a growing household or another property can change what you need. Look at the existing loan alongside your current earnings, costs and plans before deciding whether to keep it or switch.
Before you decide
Make the details work together.
The useful question is how a loan fits your position. Consider the evidence, funds and ongoing costs together, whether you’re buying or reviewing an existing loan.
Start with how you’re paid today and the documents that show it. Flag variable earnings, a recent role change or self-employment so your adviser can check the relevant lender requirements.
02Deposit, equity and commitments
Bring together the funds you can contribute, any existing property loans and your household debts and expenses. Include study debt and business commitments rather than assuming they can be left out.
03Repayments, features and total cost
Compare the ongoing repayments and fees with the features you expect to use. If you already own a home, weigh any cost of changing loans alongside the reasons for moving.
Your profession alone does not establish eligibility. Any occupation-specific lending policy needs to be checked against the current lender criteria and your circumstances.
The next steps
A clear path for your next loan.
For a purchase or refinance, start with your goal and work towards a plan with your adviser. If you want to stay with your lender, explore our negotiation service first.
01
Match
Tell us whether you’re buying or refinancing, then share your circumstances to explore matched loan options. These are indicative options, not a recommendation or approval.
02
Connect
Talk with the Wity team about your work, finances and property plans. This is a discovery conversation; credit advice comes later with your adviser.
03
Plan
Your adviser presents your WityLoanPlan and recommendation at a Strategy Meeting. Review the options, costs and trade-offs before deciding whether to proceed.
04
Settle or Switch
After you accept your loan proposal, we prepare your application and supporting documents for the lender. We work through its requirements towards your purchase settlement or loan switch.
The lender makes the approval decision. Accepting your loan proposal authorises preparation; it does not lodge an application or guarantee approval or settlement.
A little more clarity
Before you take the next step.
A few useful answers. For the details that are specific to you, talk with our team.
The information on this page is general in nature and does not constitute personal financial advice. Loan options and borrowing estimates are indicative. Credit eligibility criteria, terms, conditions and fees apply. Any occupation-specific policy is subject to current lender eligibility and full assessment.